XTimes
Editor’s Note
Only a week after the midterms and the AI industry has already felt a shift. Whether it will be longstanding or just a brief reaction to the uncertainty of a political change, remains to be seen.
What we do know is that lenders have begun refusing to finance data center deals they would have funded a month ago — in some cases even with major technology companies guaranteeing the debt. Investors knocked hundreds of billions off what they’re willing to pay for Anthropic when it lists later this month. Voters in forty of forty-one local ballot measures said no to data centers in their communities, and several governors-elect won on promises to restrict them. Microsoft declined an option to double its computing capacity in Texas. And Nvidia’s board opened an independent investigation into whether its founder had been targeted by a foreign intelligence service — a story that erased roughly $200 billion in market value in a single day, on the strength of allegations no government has publicly substantiated.
Two weeks ago, in this space, I argued that the real question about the AI buildout was who holds the risk and ended by noting that the documents are public and somebody ought to read them. This week, several somebodies did. That’s the subject of this week's Reflection. Read on.
Top Stories
The Allegation and the $200 Billion
On Sunday, Nvidia’s board of directors announced an independent investigation into reports that its founder and chief executive had been the target of a foreign intelligence operation. The precise wording matters, because much of the coverage has reversed it: “The NVIDIA Board is initiating an independent investigation in light of recent reporting that founder and CEO Jensen Huang has been the target of a foreign intelligence effort,” the statement read. “A committee of independent directors, assisted by outside independent counsel, will oversee the investigation” (CBS News). Huang is the person the board says was targeted, not the subject of a probe into his own conduct. He has said he fully supports the review and intends to continue leading the company.
The underlying reporting came from the New York Times and the Financial Times over the preceding two weeks. According to those accounts, U.S. intelligence officials believe Alice Huang — no relation to Jensen — was recruited to spy for China’s Ministry of State Security, and had a close relationship with Nvidia’s chief executive. She is a former executive of Megaspeed, a Singapore-based cloud company and Nvidia customer that has been accused of helping restricted Chinese firms obtain Nvidia AI chips. In an email to employees on Sunday, Jensen Huang acknowledged an affair (NPR).
What is and isn’t established deserves to be stated plainly. The espionage allegation rests on anonymous intelligence sources relayed through two newspapers. No charges against Alice Huang have been reported. No government agency has publicly presented evidence. China’s Foreign Ministry spokesperson Guo Jiakun called the account “entirely baseless,” constituting “slander and smear.” And Nvidia’s own spokesman, John Rizzo, said something worth reading carefully: “We trust that if we were the target of a genuine threat, the U.S. government would have notified us.” That is a company stating, in diplomatic language, that no official body has told it anything.
The market did not wait. Nvidia fell 4.3% on Monday, erasing close to $200 billion in value, and slid further Tuesday (Bloomberg). Analyst Dan Ives called the episode a “black eye” likely to generate multiple congressional investigations, while predicting Huang stays in the role near-term. Others have begun asking publicly why Nvidia’s board has not laid out a succession plan.
Why it matters: Set aside the affair, which Huang disclosed himself and which matters here only as the alleged vector. What remains is a genuinely serious question about whether the executive who controls the supply of the world’s most strategically important chips was approached by a foreign intelligence service — and a demonstration of what that question costs even before anyone answers it. Two hundred billion dollars of value moved on reporting that intelligence officials believe something, which is a lower evidentiary bar than most of us would accept for anything else. The board’s response is the appropriate one, and arguably the most encouraging part: an independent committee with outside counsel is exactly the instrument this situation calls for. But readers should hold the distinction firmly. A board investigating whether its chief executive was compromised is not the same as a board investigating its chief executive — and an allegation, however well-sourced, is not yet a finding.
Forty-One Ballots, Forty Rejections
Voters decided 41 local ballot measures on data center development on November 3. Forty of them went against the industry (Ballotpedia). Counting measures decided earlier in the fall, the research firm Redbud Consulting puts the tally at 44 of 45.
The breakdown: voters approved 27 measures that limited data center development or formally expressed opposition, and defeated 13 that would have favored or enabled it. That included five outright bans — one each in California and Florida, three in Ohio — and three six-month moratoriums, all in Maine. The measures spanned ten states, with Ohio alone accounting for 21 of them, and passed by margins commonly running three or four to one (Route Fifty). The single exception was Harwood, North Dakota, where 75% of the 430 people who voted rejected a measure that would have required independent review and a public hearing before approving large industrial projects.
The results extended well past the ballot measures. Texas elected Governor Gina Hinojosa, who campaigned on restricting data centers. Democrats won governorships in Ohio, Georgia, Iowa, and Nevada — states where the governor has real leverage over siting and utility policy — and several incoming governors, Texas included, have called for an immediate moratorium on new development (U.S. News). In Georgia, Public Service Commissioner Peter Hubbard, who had pushed to reconsider a grid expansion request tied to data centers, won re-election.
It's worth noting that these were local measures, in jurisdictions where the issue was salient enough to reach a ballot — typically smaller and more rural communities. There were no statewide or national data center measures on November 3. Industry analysts reading the results as place-specific rather than a national mandate have a point, and the distinction will matter when the fight moves to state legislatures.
Why it matters: We’ve tracked this backlash since August, when 75 projects worth $130 billion were blocked or delayed in a single quarter and Gallup found roughly 70% of Americans are opposed to a data center in their own community. What changed on November 3 is that the opposition stopped being a polling result and became an electoral one — and it did so in both red and blue places, which is why it has moved so fast. The industry now faces a problem it cannot solve with capital: not whether it can afford to build, but whether anyone will let it. That is a different kind of constraint than chips or power, and it will shape the next two years more than either.
Wall Street Gets Cautious
On Thursday, November 5, the Nasdaq 100 lost roughly $2.5 trillion in market value. By Monday, Reuters reported that banks and credit investors had sharply increased their scrutiny of AI-related debt and grown reluctant to add exposure — in some cases declining to finance deals even when major technology companies guarantee the payments (Reuters via Kitco).
The specifics are more informative than the mood. Spreads on ten-year hyperscaler debt have widened about 50 basis points this year, against roughly 20 for high-quality industrial borrowers with no AI exposure, according to Bank of America credit analyst Yuri Seliger — and some recent large bond issues have traded below their offering price. The neocloud firm Nebius had been exploring a high-yield bond in September and shelved it. Other planned offerings tied to data centers and chips are reportedly on hold. Lenders have begun stress-testing cash flows against downturn scenarios, leaning harder on debt-service-coverage ratios and refinancing risk, and discounting contracts that customers can shrink or cancel quickly. At JPMorgan, loans backed by income-producing properties including data centers stood at $29 billion at the end of the third quarter — up from 8% of the bank’s commercial real estate book three years ago, when data centers ranked fourth behind apartments, industrial properties, and offices.
Two things complicate the “turn” narrative. Goldman Sachs Research still projects global hyperscaler debt issuance reaching $420 billion in 2027, more than 60% above this year’s estimated $250 billion — meaning demand for this financing is expected to grow substantially even as lenders get choosier. And the Nasdaq had largely rebounded by Monday. Banks tightening after a bad Thursday and an election is among the most ordinary things in finance, and sentiment reverses on the same schedule it arrives.
The same week brought a concrete example of a buyer stepping back. Microsoft declined an option to more than double its contract with the British AI infrastructure firm Nscale at its Ward County, Texas site — roughly 500 megawatts, potentially worth tens of billions (Reuters). Here too the explanations differ and the differences matter: the Financial Times framed it against the political environment, Bloomberg reported the project was stalled awaiting regulatory approval for its energy connection, and a person familiar with the decision told Reuters it was made several months ago, before Nscale filed for its IPO in September, with the existing Texas contract unaffected. Microsoft also withdrew last month from Nscale’s flagship Essex project after power delays pushed supply into the 2030s, while maintaining partnerships in Portugal and Norway. Nscale, which is Nvidia-backed and preparing a roughly $35 billion offering, posted a $1 billion net loss on $141 million of revenue in the first half of this year; its $103 billion backlog is unchanged. (Disclosure: Nscale’s West Virginia site anchors a $45 billion computing agreement with Anthropic, which makes the AI model used to research this newsletter. That site has faced construction delays and local opposition.)
Why it matters: Readers of our “Circle of Risk” essay two weeks ago will recognize precisely which arrangements are now being examined — the special purpose vehicles, the residual value guarantees, the leases with cancellation terms. What’s being stress-tested this week is exactly what we described then, by the people whose money is in it. That is the system working as designed, not failing. The caution is warranted on both sides: one week of lender hesitation after a selloff is a mood, not a verdict, and the Bank of England flagged AI-infrastructure debt as a stability concern back in July, long before this week. What’s genuinely new is not that the money got nervous. It’s how many different parties got nervous at once. Whether this is truly a long-term shift or short-live reaction remains to be seen.
Anthropic Prices Into a Downturn
(Once again, while its editor is human, Anthropic makes the AI model used to research this newsletter. Read accordingly.)
In an updated securities filing Tuesday, Anthropic set a tentative valuation for its initial public offering of $1.26 to $1.4 trillion, seeking to raise roughly $90 billion (The Information). That is a substantially lower figure than the company was expected to command five weeks ago, and the descent tracks the market almost exactly.
In early October, prospective buyers were discussing valuations as high as $2 trillion. By mid-October, following an investor day covering Anthropic’s financial performance, the conversation had moved to around $1.5 trillion. After Thursday’s selloff, Bloomberg reported prospective investors discussing $1.2 to $1.3 trillion — with some considering figures as low as $1.1 trillion, and the Wall Street Journal reporting that three major prospective investors wanted even lower pricing, one suggesting closer to $1 trillion (Quartz). One investor told CNBC that $1.5 trillion was “a stretch.”
The process has been bumpy in public. On Monday, Anthropic emailed bankers a price range of $70 to $80 per share, then retracted the communication and said correct pricing would be announced shortly; the retracted filing indicated 867 million shares and a raise of up to $69.3 billion, implying roughly $1.4 trillion (Yahoo Finance). Investors are also waiting on one specific number: Anthropic’s October revenue, which the company left blank in its updated S-1. The roadshow was expected this week with pricing to follow, and the company is still targeting a listing before Thanksgiving.
Why it matters: A $1.3 trillion debut would still be the largest initial public offering in history by a wide margin — SpaceX’s record was $86 billion raised at a $1.77 trillion valuation — and it would represent extraordinary growth for a company founded in 2021. It would also be roughly a third less than what buyers were discussing in early October, for a company whose fundamentals did not change in the interim. What changed was the price of risk. That is what public markets do that private rounds do not: they produce a number set by people with their own money at stake rather than by negotiation between parties who both benefit from a higher figure. Whatever Anthropic prices at, the discovery of that number in public is the useful part.
Quick Picks
Six Pallets, Gone
On August 29, a truck collected six pallets of Nvidia hardware in Oakland, bound for Fort Worth. Because GPU shipments have become a target, the truck carried the logo of a food transportation company — a disguise meant to keep thieves from identifying valuable freight. The shipment, reportedly worth $11.4 million, never arrived. (San Francisco Chronicle).
The truck went off the grid heading south, made several multi-hour stops, and investigators lost track of it in San Bernardino County. Nobody realized the cargo was missing until early September; Oakland police were notified on September 13. No arrests have been announced, nothing has been recovered, and police have not confirmed the valuation, identified what was on the pallets, or explained how the theft was accomplished. The disguise didn’t work, which suggests the thieves likely knew what was on those pallets before the truck left Oakland.
The economics explain the surge. “If a chip costs about $550,000, then they go for about $1 million or more abroad,” UC Berkeley’s Olaf Groth told ABC7. He is describing data center hardware rather than consumer graphics cards — the six stolen pallets averaged roughly $1.9 million each — and stolen components can be stripped for gray-market resale or routed to countries where American hardware is restricted. Fremont and Union City police investigated more than $7.5 million in Nvidia cargo burglaries last year. Roughly $100 million in data-center-bound freight has been taken off American highways since June, with thieves reported ramming escort vehicles and spoofing GPS. Because hyperscalers schedule GPU deliveries months in advance, a single stolen load can delay a facility’s commissioning. Copper used to be what disappeared from job sites. Now it’s accelerators.
The Cybertruck Winds Down
Elon Musk announced Friday that Tesla will be “winding down production of the Cybertruck at Gigafactory Texas around the middle of next year to make room for increased Cybercab production” (Forbes). On Monday he added that deposits will be refunded: “We will try to make as many as possible before shutting down the line in about 8 months, but will have to return deposits for a lot of people.”
The sales record explains the decision. Tesla sold 20,237 Cybertrucks in 2025 and 11,586 through the first three quarters of 2026, against installed capacity of more than 125,000 a year at the Texas plant. Third-quarter deliveries in the “Other Models” category — which groups the Cybertruck with the Model S, Model X, and Semi — fell 48% year over year to 8,295 units, the lowest since mid-2021. Musk once announced 250,000 preorders in the five days after the 2019 unveiling. Bloomberg has compared the vehicle to Ford’s Edsel; CNN reports it appears Tesla intends to discontinue it entirely rather than move production elsewhere.
One oddity: Musk’s stated reason for refunding deposits is that orders exceed production capacity, which sits awkwardly beside a plant running at under a tenth of its capacity and sales falling by half. Both things may be true in some narrow sense — a wind-down compresses the window regardless of demand — but the framing is generous. Note also what the capacity is being redirected toward: the Cybercab, the steering-wheel-free robotaxi that began carrying passengers in Austin in September. Tesla is converting a factory built for drivers into one built for their absence.
✔ Our next Singularity Circle will occur Saturday, December 5, 2026, at 10:00 AM Pacific Time. As usual, a Zoom link will be sent to eligible members in advance of the gathering.
✔ Exponential Times will return on November 17th with all the latest technology news.
✔ The Singularity is Near, Not Here is Singulairty Sanctuary's latest video production exploring the question of what the Singularity means and when it will occur.
The Optimist’s Reflection
The Question Everyone Started Asking
By Todd Eklof
Two weeks ago I ended my weekly reflection by pointing out that Anthropic’s prospectus was free to download, that the risk factors ran for ninety-four pages, and that somebody ought to read them.
Judging by this week's news, it seems apparent that several somebodies did.
Just since last Thursdays, lenders at major banks began declining to finance AI data center deals — including, remarkably, deals where large technology companies guarantee the payments, something they were willing to do just a few weeks ago. They also began stress-testing cash flows against recessions and discounting contracts that customers can cancel quickly. Which is to say: they began examining precisely the structures I described in that essay, the special purpose vehicles and residual guarantees and leases, and asking what they’re actually worth if demand disappoints.
Meanwhile, prospective investors in Anthropic’s public offering moved their estimate of the company’s value from around $2 trillion in early October to a range of $1.26 to $1.4 trillion today. The company didn’t change. The price of risk did.
In forty of forty-one local ballot measures, American voters said they did not want a data center in their community. Several governors-elect won on promises to restrict them.
And Microsoft declined an option to double its computing capacity in Texas — an option worth tens of billions of dollars.
Four different groups of people, with nothing in common and no way to coordinate, all asked the same question in the same week: is this worth what we’re being told it’s worth?
Still, it's too early to turn this into a narrative about a bubble popping, which I don’t think is what's happening. Banks tightening credit after a bad Thursday and a surprising election is among the most ordinary things in the history of finance. Goldman Sachs still expects hyperscale borrowing to rise more than 60% next year. The Nasdaq had mostly recovered by Monday. So, one week of caution is likely a mood, not a verdict.
What strikes me isn’t that the money tightened up, at least for now. It’s how many different instruments did their job at once, and how little they needed anyone’s permission.
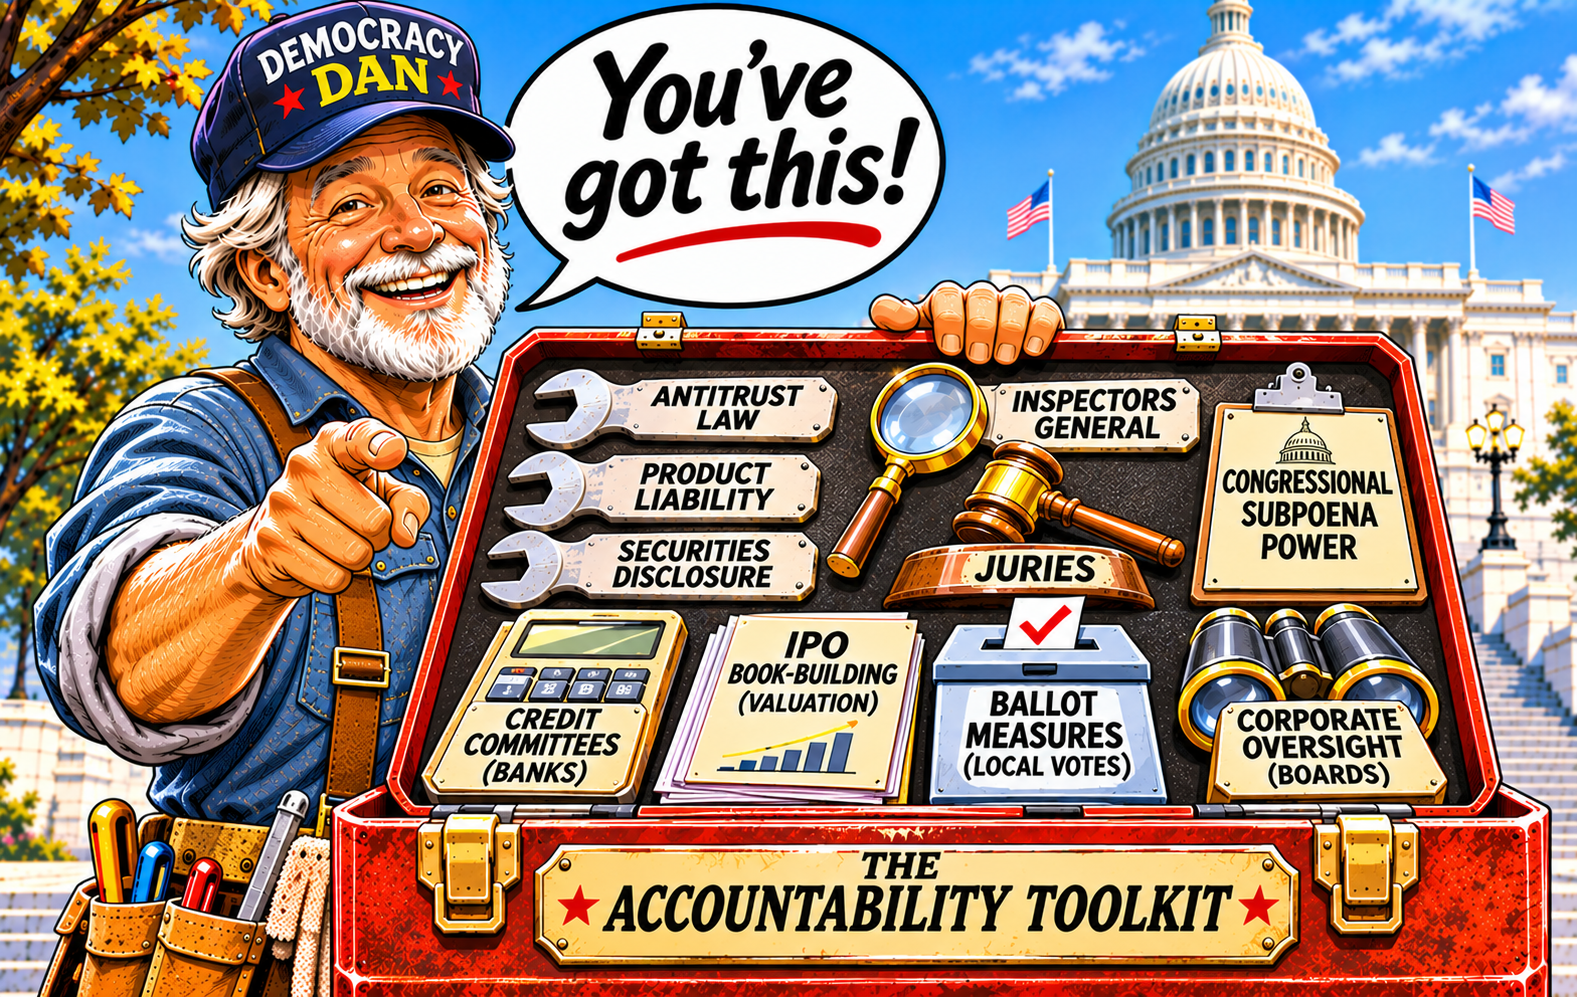
Last week I wrote about the East India Company, and about the historian William Dalrymple’s observation that the tools for holding concentrated private power accountable still exist — what’s lacking is the impulse to use them. This week several of those tools were put to use.
A credit committee at a bank is an instrument of accountability. So is an IPO book-building process, which forces a private valuation into contact with people who have to risk their own money on it. So is a township ballot measure in Ohio. So, for that matter, is a corporate board hiring outside counsel to investigate whether its own founder was compromised by a foreign intelligence service — which is what Nvidia’s directors did this week, before any regulator asked them to.
No one organized. Nobody marched. No new laws or regulations were passed. A loan officer re-ran a model with worse assumptions. An investor said the number was too high. A few hundred people in Harwood, North Dakota voted, and in forty other towns voted the other way. These are the small mechanical motions by which a society actually prices things, and they are mostly the way anything ever gets corrected.
Since this has also been a week that rewards humility, I should mention what I don't know. I don’t know whether Anthropic’s lower valuation is the market finding the right number or overshooting in a panic. I don’t know whether lenders will still be cautious in January. I don’t know whether the allegations concerning Nvidia’s chief executive will prove out — no government has made its evidence public, the company says nobody official has even contacted it, and two hundred billion dollars moved on reporting that intelligence officials believe something. That gap between what is known and what is priced should give all of us pause, in both directions.
What I do know is that a month ago these questions were being asked almost exclusively by critics, and this week they were asked by the people writing the checks.
That’s the piece worth noticing. The strength of an open system isn’t that it gets things right the first time. It’s that it contains a very large number of people with independent reasons to check, and no single actor who can stop all of them from checking at once. The banker and the voter and the fund manager and the board member were not collaborating. They weren’t even aware of one another. They simply each had a stake, and access to the information, and the ordinary human instinct to ask whether the story is adding up.
Sometimes that produces panic. Sometimes it produces accuracy. Usually, it takes several rounds to tell which.
But I’ll take a week in which everyone started asking over a year in which nobody did. The prospectus was free the whole time. People are reading it now.
If you're interested, you can still Read it here
Exponential Times is published weekly by Singularity Sanctuary. To subscribe or learn more, visit singularitysanctuary.com.